Student loan debt affects millions of borrowers. Although it can be a burden, it's also an opportunity to establish a positive credit history.
Making progress towards paying down your student loan debt is possible no matter where you start. This guide from Freedom Debt Relief covers 11 smart ways to pay off student loans, from simple payment tweaks to federal programs that could lower your balance. Each strategy below is practical and easy to put into action, so you can find the ones that fit your situation.
Key Takeaways:
Make extra payments to pay down the principal and speed up loan payoff.
Explore loan forgiveness programs for federal loans, which may cancel your remaining balance after a set number of qualifying payments.
Use debt snowball or avalanche methods to stay motivated and minimize interest.
Confirm your loan balances and servicer before you choose a payoff strategy.
Find Your Loans and Loan Servicer
Before you choose a payoff strategy, confirm exactly what you owe and who services each loan. Log in to StudentAid.gov to find your federal loan balances, interest rates, and servicer. Check your account statements or credit report to identify private loan balances and lenders, since private loans don't show up on StudentAid.gov.
Your loan servicer handles your payments, so contact them directly with account questions or to ask about repayment programs. Beware of repayment scams. Legitimate servicers don't ask for payment through gift cards and don't guarantee loan forgiveness in exchange for an upfront fee. Confirm the servicer contact information against your official loan documents before you share personal or financial information.
A full loan picture also helps you compare the 11 strategies below and choose the ones that fit your budget and your loan type.
1. Make Extra Payments on Your Student Loans
If you want to pay off your student loans more quickly, one of the best ways is to make extra payments toward your loans. You could potentially shave years off your repayment plan.
Ask your loan servicer to put the money toward the loan principal. Otherwise, your servicer might use the money for the next month's payment. If you have multiple loans, pick one to focus on.
Here's how to make extra payments on your student loan:
Log in to your online portal to make a payment.
Select custom or manual allocation.
Select the loan you want your extra payment to go toward.
Tip: Biweekly payments could help you pay off loans even faster.
2. Refinance Your Student Loans
Refinance or consolidate student loans to streamline your finances. When you refinance, you combine your existing loans into one new loan.
If you have private student loans, you might lower your interest rate by refinancing. If you have federal loans, your interest rate generally stays the same. That means private student loans are generally better candidates for refinancing than federal ones.
You could benefit from refinancing if you have:
A good credit score (above 670)
Predictable, consistent income
Low debt-to-income ratio
Private student loans with high interest rates
Federal student loans are typically only worth refinancing if you don't forfeit the benefits that come with those loans. Federal and private loans should generally stay separate. When you fold federal loans into a private loan, you lose government benefits such as access to income-based repayment programs and potential loan forgiveness in the future.
3. Use the Debt Snowball Method for Quick Wins
Students often get out of school with multiple student loans. The total may add up to an amount that seems impossible to budge, but when your loan balance seems frozen, you may be able to get it rolling with the debt snowball method. This method targets the loan with the smallest balance first.
How to use the debt snowball:
List your debts from smallest to largest balance.
Make the minimum payment on each of those debts.
Put any extra funds you can find toward the smallest debt (in addition to the minimum payment).
After clearing the smallest debt, roll its payment and any extra funds into your payment on the next smallest debt.
Repeat.
The debt snowball strategy rewards you with quick wins—it's the fastest path towards reducing the number of debts you have.
4. Save on Interest With the Debt Avalanche Method
The debt avalanche strategy could help you pay less interest. This method targets the debt with the highest interest rate.
How to use the debt avalanche method:
List your debts from highest to lowest interest rate.
Pay the minimum on each of those debts.
Put all your extra cash toward the debt with the highest interest rate, in addition to its minimum payment.
Once you pay off the highest-interest debt, move that entire payment to the debt with the next-highest rate.
Repeat.
The avalanche strategy could help you clear your most expensive debt first and save on interest over the long run. Reducing interest costs can be a path to paying off your total debt sooner.
5. Set Up Autopay for Smart Discounts
The Federal Student Aid government website suggests you set up autopay, also called automatic debit, to save money. Autopay is smart because it helps you avoid missed payments, which can result in late fees.
Some loan servicers reduce your interest rate by 0.25% when you automate payments.
How to enroll in autopay:
Log in to your loan servicer's website or mobile app.
Find an "Autopay" or "Automatic Payments" section.
See if there's a discount for enrolling in autopay.
Follow the prompts to set up your automatic payments and choose your payment method.
6. Make Interest-Only Payments Before Graduation
Federal loans for undergraduates come in two flavors: unsubsidized and subsidized.
On subsidized loans, interest doesn't begin to accrue until after graduation.
On unsubsidized loans, interest accrues from the day you get the loan. It continues until you pay off the entire balance.
So, for example, if you took an unsubsidized loan out your freshman year, interest accrues on that loan throughout your time in college, even during times when payments aren't required. When your loan status changes to repayment status (usually at the time you graduate), your servicer capitalizes any interest that accrued on unsubsidized loans. Capitalized interest means your servicer adds the unpaid interest to your loan balance. Then you'll pay interest on the new, higher amount.
Capitalized interest increases the total amount you repay.
You could reduce the impact of interest capitalization by paying at least enough to cover the interest charged each month, even before you graduate. These small payments could leave you with significantly less debt after graduation.
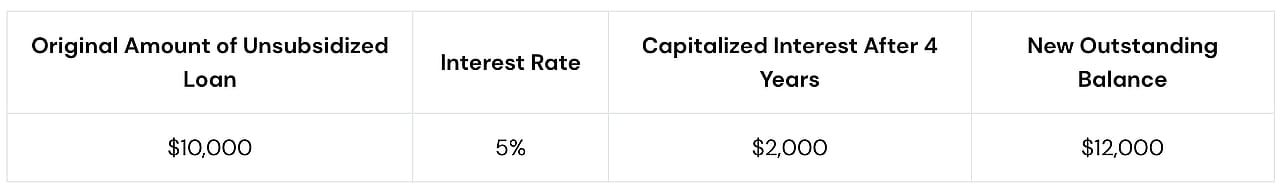
For example, say you take out a $10,000 unsubsidized loan with a 5% interest rate in your freshman year. After you graduate in four years, you'll owe the original $10,000 plus $2,000 in interest that accrued during your time in college. This would leave you with a total debt of $12,000, as shown below:
Freedom Debt Relief
It would cost just under $42 a month to cover those interest payments while you're in school. This would leave you with $2,000 less debt when you graduate.
7. Stick to Standardized Student Loan Repayment Plans
Depending on your loan, you may be eligible for a plan that allows you to pay off your loan over a longer time, resulting in lower payments. While those payments may be easier to afford from month to month, an extended repayment period will mean being in debt longer and is likely to cost you more in interest charges in the long run.
The 10-year standard repayment plan pays off loans faster than extended plans, which run up to 30 years and increase total interest. The standard plan works well if you have a stable income.
Federal repayment plans changed under the One Big Beautiful Bill Act, effective July 1, 2026. Newer federal loans use a Repayment Assistance Plan (RAP), an income-driven option, or a tiered standard plan with a repayment period between 10 and 25 years.
If you already have federal loans and don't take out new ones after July 1, 2026, you may be able to keep your current plan. Borrowers in the SAVE, PAYE, or ICR plan must switch to an eligible plan by July 1, 2028. Check your servicer account for the plans available to you, since eligibility depends on when you took out your loans.
8. Build a Budget That Supports Your Loan Payments
A budget shows exactly how much you have available for loan payments each month. First, list your income and fixed expenses, such as rent, utilities, and groceries. Subtract those totals from your take-home pay to find what's left for debt payments and savings.
Small changes add up. Cut a subscription or another recurring expense by $20 to $50 a month to free up cash for your loan principal, on top of your regular payment. Review your budget every few months, since your income and expenses change over time.
A budget can also help you decide how to spend any financial windfalls or extra earnings.
9. Spend Windfalls on Student Loans
Put some of the money from raises, bonuses, tax refunds, or side hustle earnings towards loan payments. Any amount helps, even an extra $20 a week from walking dogs, or a portion of your holiday bonus if you get one.
10. Ask if Your Employer Helps With Student Loans
Find out from HR if your company has a student loan assistance program.
Employer assistance is a smart way to pay off student loans, and it benefits both you and the employer. Employers get a tax break for offering these benefits.
Employers might offer up to $5,250 annually in tax-free student loan repayment and tuition assistance per employee. This benefit no longer has an expiration date, and the IRS will adjust the amount for inflation starting in 2027.
11. Explore Smart Loan Forgiveness Programs
Federal student loans offer several forgiveness programs that private lenders don't provide.
Public Service Loan Forgiveness (PSLF). Work full-time for a government or nonprofit job, make 120 qualifying payments, and you could apply to have the remaining balance on your Direct Loans forgiven.
Income-Driven Repayment (IDR) Plan. Payments are based on your income and family size for 20 or 25 years, depending on the plan. The plan forgives any balance that remains after that.
Teacher Loan Forgiveness. Teach five years straight at a low-income school, and you could get up to $17,500 knocked off your Direct or FFEL Loans.
Total and Permanent Disability (TPD) Discharge. If a serious disability stops you from working, the government may discharge (forgive) your Direct, FFEL, or Perkins loan. You'll need proof from the Social Security Administration, Department of Veterans Affairs, or a doctor.
Military Service Benefits. Military folks get benefits like a 6% capped interest rate and deferments, courtesy of the Servicemembers Civil Relief Act (SCRA). Your service generally also counts toward PSLF.
Segal AmeriCorps Education Award. Complete a term of service with AmeriCorps to receive cash toward your loans. The award amount changes each year. It was $7,395 for a full-time term completed in 2024. Completing a term of service might also help with PSLF.
Visit StudentAid.gov and the Consumer Financial Protection Bureau for more information about federal loan forgiveness programs.
Student Loan Debt Relief
Debt relief may be available even if you only have private student loans. Private loans don't qualify for federal programs, and you can't consolidate them into federal loans. Private student loans are unsecured debt, so options like private debt consolidation or a debt settlement program are worth exploring.
Consider the range of private student loan debt relief options before you commit. Options exist for a wide variety of circumstances, and many borrowers find a debt relief method that fits their situation.
Debt settlement may negatively impact your credit.
Take the Next Step With Your Student Loans
Real progress on student loan debt is possible, no matter where you're starting. Explore the debt relief options above to find the ones that fit your situation, whether you're managing high credit card balances, several tradelines, or just your student loans.